Defend against personal tax liability
Has a German tax office sought to hold you personally liable for another person’s tax debt? We review the liability basis, underlying tax claim, fault, discretion and deadlines and represent clients nationwide in Germany.
What a notice of liability means
Being held liable for third-party taxes with private assets
A German tax liability notice can expose a managing director, board member, business acquirer or other person to personal payment liability for taxes owed by a company or another taxpayer. The notice is generally issued under Section 191 of the German Fiscal Code (Abgabenordnung – AO). For managing directors and other statutory representatives, Sections 34 and 69 AO are often central.
Personal liability does not arise merely because taxes remain unpaid. Depending on the statutory basis, the German tax authority must establish the relevant duties, breach, fault, causation, amount of the underlying tax debt and a lawful exercise of discretion.
If the notice has already been served, the objection deadline should be secured immediately. An objection does not generally suspend enforcement. We therefore also assess whether an application for suspension of enforcement should be filed.
Proven Professional Experience
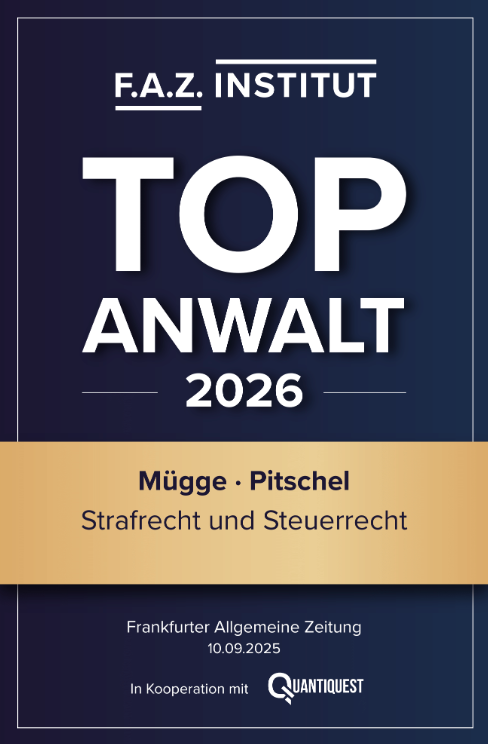
Complex proceedings demand proven experience and specialized expertise. That is why we feature only awards and credentials that are current and verifiable.
 TOP Lawyer 2026 & 2027 for Criminal Law and Tax Law
- Certified Specialist Attorneys for Criminal Law and Tax Law
- Certified Consultants for Criminal Tax Law and White-Collar Criminal Law (DAA)
What matters now
The first steps after receiving a German tax liability notice
Keep the complete German liability notice, all annexes and calculations, the legal-remedies information, underlying tax assessments and prior correspondence. In managing-director cases, documents on responsibilities, liquidity and payments are often particularly important.
The review should not focus only on the amount. We first identify the statutory liability provision, the relevant periods and whether the personal claim is legally and factually sustainable.
Important: An objection against a German tax liability notice generally does not suspend enforcement. If payment or enforcement is imminent, suspension or cancellation of enforcement must be considered separately.
Secure the appeal period
The appeal must generally be filed within one month of notification.
To the appeal procedure
Note the enforcement
The appeal does not stop the payment obligation. A suspension of enforcement must be requested separately.
Review the liability norm
First, we clarify which norm the tax office is relying on and which period the notice covers.
Don't just talk about the amount
The decisive factor is whether the personal liability claim is legally and factually sustainable.
How we help
From tax debt to discretionary decisions
We review the liability notice, the underlying tax debt, the statutory liability basis, fault and causation, and the German tax authority’s discretionary decision. We then conduct the objection proceedings, seek suspension of enforcement where appropriate and represent clients in German tax court proceedings. This page is part of our German Tax Law practice.
01
Review the liability basis
We identify the statutory provision relied on by the German tax office and test whether its personal, substantive and temporal requirements are met.
02
Reassess the underlying tax debt
The underlying tax claims, calculations, payments and assessment issues are reviewed separately. A liability notice should not simply carry forward an incorrect primary tax debt.
03
Review administrative discretion
We review the authority’s decision and selection discretion, its reasoning and whether all material circumstances for and against personal liability were taken into account.
04
Secure objection and enforcement protection
We secure the objection deadline and assess suspension of enforcement so that the legal remedy is not economically undermined by immediate payment or enforcement.
Managing director liability
Separate breach of duty, fault, and causality
According to § 69 AO, managing directors are only liable if they have violated tax duties intentionally or through gross negligence, resulting in taxes not being assessed or paid, or not being assessed or paid on time. It depends on the distribution of tasks, liquidity, use of funds, and due dates.
Blanket attributions of responsibility are not sufficient for a sustainable liability decision. We organize periods, tax types, due dates, and payments so that the scope of liability and causality become verifiable.
Typical scenarios
Who is frequently held liable
What these cases have in common is that the tax office wants to enforce a third-party tax debt against another person.
- Managing directors and board members (§§ 34, 69 AO)
- Persons to whom tax evasion is attributed (§ 71 AO)
- Those responsible for wage tax and other withholding taxes
- Business transferees and controlled companies (§§ 73, 75 AO)
- Association officials
- Cases with multiple potential liability debtors
When tax evasion is alleged at the same time
If an allegation of tax evasion looms alongside liability, tax law and criminal law statements must be coordinated. In such cases, we involve tax criminal law from the very beginning.

Your contact persons
Who will review your notice of liability
Our specialist attorneys for tax law represent managing directors, board members, and other responsible parties nationwide against personal liability claims.
Meet our team
Benienja Kirschbaum
Office Management
Carolina Mügge
PA to CEO
What our clients say


 (opens in a new tab)
 (opens in a new tab)
 (opens in a new tab)
 (opens in a new tab)
 (opens in a new tab)
 (opens in a new tab)
 (opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)(opens in a new tab)
Questions about the notice of liability
Notice of liability according to § 191 AO
Confidential initial inquiry
Received a notice of liability?
Briefly describe which tax types and periods are affected, which liability norm the tax office is relying on, and when the notice was issued. We will review the deadline, the grounds for liability, and the further course of action.
Call directly