November 25, 2024
|
in Tax Law
by Dr. Anthea Pitschel
Key Facts at a Glance: Objection to a Tax Assessment Notice (Income Tax Notice)
- Tax Assessment: The tax assessment notice determines whether you owe an additional payment or will receive a refund.
- Errors Are Common: According to the German Taxpayers Federation, roughly one in five tax assessment notices contains errors.
- A Review Pays Off: Verify figures, allowances, extraordinary expenses, and discrepancies compared to your return.
- Filing an Objection: You can file an objection with the tax office against an erroneous tax assessment notice.
- Deadline: You have only one month following notification to do so.
- Legal Assistance: An attorney specializing in tax law can identify errors, substantiate arguments, and ensure deadlines are met.
Objection to a Tax Assessment Notice – The Proper Procedure
Every year, millions of taxpayers receive a tax assessment notice—often accompanied by questions, uncertainty, or frustration. If the notice contains errors or deviates from your tax return, the question quickly arises: Should I file an objection against the tax assessment notice, and when is it truly worth doing so?
In this article, you will learn how a tax assessment notice is structured, what typical errors occur, and how to effectively exercise your rights to correct erroneous assessments.
What Is a Tax Assessment Notice?
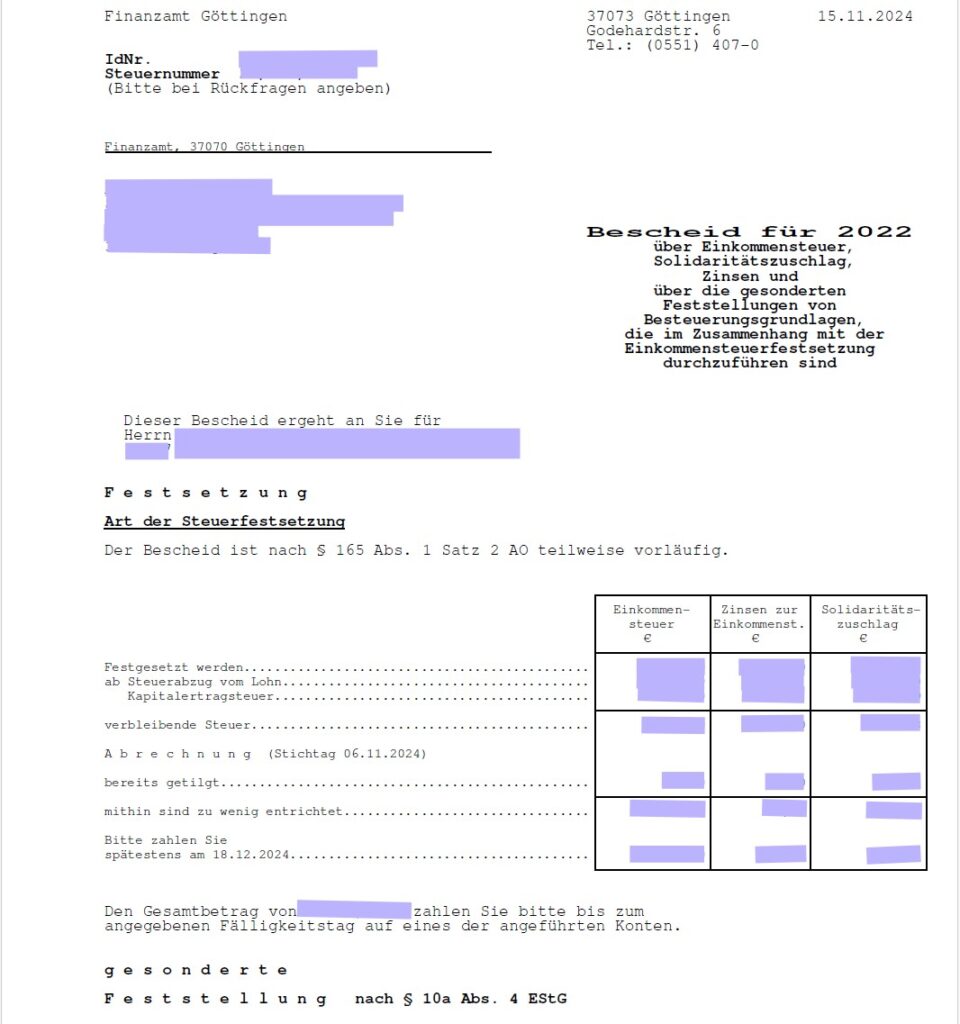
The income tax assessment notice (or simply tax assessment notice) is the official document by which the tax office reviews your submitted tax return and makes a legally binding assessment of your tax—either resulting in a refund or an additional payment.
It provides a detailed breakdown of how the tax office reached its determination: which income was taken into account, which deductions and allowances were recognized, and where discrepancies with your return exist.
The Tax Return as the Basis for the Tax Assessment Notice
The mandatory basis for the tax assessment notice is your filed tax return. It can be submitted in traditional paper form or—now standard—digitally via ELSTER or dedicated tax software.
Electronic submission reduces errors and frequently results in faster processing by the tax office. Nevertheless, you should anticipate an average processing time of 6–8 weeks.
If you have not received an assessment after more than six months and the tax office has made no inquiries, you can file an objection for failure to act.
Structure of a Tax Assessment Notice
A tax assessment notice often appears complex, but it follows a statutorily prescribed standard structure. Certain components must be included (mandatory provisions), while others should be included (directory provisions).
Mandatory Elements (Errors → notice may be void):
- Type of tax
- Amount of tax assessed
- Tax debtor (taxpayer)
- Competent tax office
If these are missing, the notice may be void pursuant to Section 125 of the German Fiscal Code (AO).
Directory Elements (Omission = notice remains legally effective):
- Statement of grounds (reasoning)
- Notice of legal remedies
Errors in either area may make an objection to the tax assessment notice necessary.
The Structure of a Tax Assessment Notice – Explained Clearly
1. Page One: Personal Details + Tax Assessment
Here you will find:
- Your personal information
- Type of tax and tax year
- Assessed tax amount
2. Pages Two and Three: Computation & Tax Bases
The tax office itemizes in detail:
- Your income (e.g., from employment, rental property, self-employment)
- Your income-related expenses, special expenses & extraordinary burdens
- Which items were allowed or disallowed
This section reveals the most common errors that may subsequently serve as grounds for an objection.
3. Explanatory Notes + Notice of Legal Remedies
The explanatory notes detail why specific figures were adjusted or disallowed.
The notice of legal remedies explains how and by when you can file an objection.
If this notice is missing, the objection deadline is extended from one month to one year (Section 356 AO).
Objection to a Tax Assessment Notice – When It Makes Sense
As soon as you receive your tax assessment notice, you should review it promptly and thoroughly. Even though a tax assessment notice is an official administrative act, it is prepared by individuals—and errors are frequent.
In fact, statistics from the German Taxpayers Federation reveal that one in five tax assessment notices contains errors.
To ensure yours is not among them, pay particular attention to:
- Formal details: personal information, address, Tax ID
- Calculation errors or transposed digits
- Disallowed income-related expenses, special expenses, or tax allowances
- Discrepancies between your tax return and the assessment notice
If you notice any discrepancies, lodging an objection is generally advisable and warranted.
Requirements for Filing an Objection to a Tax Assessment Notice
An objection must fulfill specific legal requirements to be admissible.
1. There Must Be Grounds for an Objection
These include:
- Erroneous calculations
- Unexplained deviations from the tax return
- Disallowed expenses (e.g., income-related expenses, extraordinary burdens)
- Incorrect categorization of income
2. Adherence to the Objection Deadline
The deadline is one month from notification of the assessment notice (Section 355 AO).
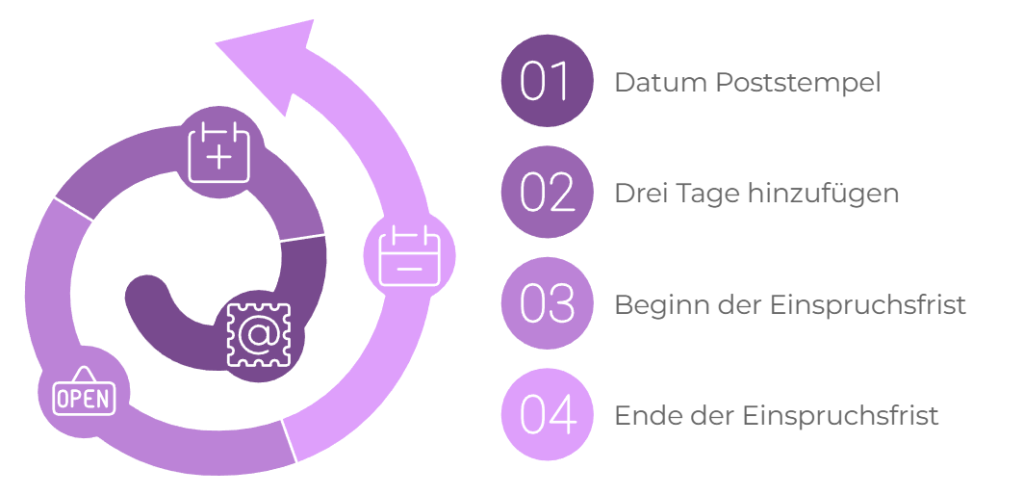
Notification = Date of the notice + 3 days postal transit time.
Example:
- Postmark date on the tax assessment notice: December 1
- plus deemed service of the administrative act (3 working days): + 3 days
- Start of the objection period: December 4
- End of the objection period: January 4
If the notice of legal remedies is defective or omitted, the deadline is extended to one year (§ 356 AO).
3. Formal Requirement: The Objection Must Be in Writing
The objection must contain the following:
- Your name and address
- Identification of the assessment notice, including the tax year
- A statement indicating that you are filing an objection
A statement of grounds is not mandatory, but it is strongly recommended, as it significantly enhances the prospects of success.
Consequences of an Objection – What Happens Next?
1. The Tax Office Re-Examines the Assessment
The objection leads to a comprehensive re-evaluation free of administrative fees.
2. Important: No Automatic Suspensive Effect
Filing an objection does not stay your obligation to pay.
In the case of disputed back payments, an application for suspension of execution (AdV) can be submitted.
If the application is rejected and the assessment is not subsequently modified in your favor, suspension interest (0.5% per month) may be charged.
3. Reformatio in Peius (Detrimental Alteration) Is Possible
The tax office is permitted to examine points that you did not dispute—and may identify errors to your detriment.
However: You must be notified in advance and have the option to withdraw your objection.
4. Rejection → Decision on Objection → Tax Court
If the tax office maintains its position, it will issue a formal decision on the objection (Einspruchsentscheidung).
You may file a lawsuit before the Tax Court (Finanzgericht) against this decision.
How Can We Assist You with Errors in Your Tax Assessment Notice?
We review your tax assessment notice, pinpoint sources of error, and draft a legally robust substantiation for your objection designed to maximize your prospects of success.
We reliably identify even complex or concealed errors, calculation mistakes, and inadequately considered deductions.
In every instance, our well-established law firm specializing in criminal law and tax law provides you with trusted counsel and efficient legal representation.
Do You Wish to File an Objection Against Your Tax Assessment Notice?
As a specialized law firm in criminal and tax law, we represent you competently and assist you in developing a tailored strategy.
Frequently Asked Questions About Objections to Tax Assessment Notices
What does a tax assessment notice look like?
In Germany, a tax assessment notice follows a standardized structure. On the first page, you will find:
- Your personal information
- the type of tax and the tax year
- the amount you are required to pay or will receive as a refund
In the event of an additional tax payment, the notice will also include:
- bank details of the tax office
- payment due date.
The second and third pages provide an overview of your income, deductions, and tax calculation. If any claimed figures were disallowed, the tax office must justify this in the explanatory notes. The final page contains the notice of legal remedies.
What should you do if the tax assessment notice is incorrect?
If there are errors, you should file an objection against the tax assessment notice. The deadline for filing is one month from notification (date of the notice + 3 days). Typical errors include:
- Calculation errors or transposed digits
- Unrecognized income-related expenses
- Incorrect marital status details
- Overlooked tax allowances
We evaluate whether an objection is advisable and offers good prospects of success.
When is it worth filing an objection against a tax assessment notice?
An objection is particularly worthwhile in cases involving:
- Discrepancies compared to your tax return
- Erroneous or contradictory calculations
- Disallowed expenses (e.g., income-related expenses, special expenses)
- Ambiguities in the assessment computation
What are the requirements for filing an objection against a tax assessment notice?
An objection against a tax assessment notice must generally be filed in writing within one month of service. If the detailed justification cannot be provided immediately, the objection can initially be submitted without comprehensive grounds to protect the deadline. The statement of grounds can then be submitted at a later date.
What are valid grounds for filing an objection against a tax assessment notice?
The most significant grounds include:
- Calculation and clerical errors
- Incorrect categorization of income
- Unrecognized double household maintenance expenses
- Disallowance of extraordinary burdens
- Incorrect application of child tax allowances
We examine whether the determinations are correct in fact and in law.
How do I file an objection against my tax assessment notice?
The objection must be received in writing by the competent tax office and should contain:
- Name
- Address, type of tax, and tax year
- Tax file number / reference number
- Statement: “I hereby lodge an objection.”
A detailed explanation of grounds can be submitted subsequently; however, it should not be omitted, as it substantially increases the likelihood of success.
Can I still file an objection after the deadline has expired?
Yes, under exceptional circumstances:
- Defective or missing notice of legal remedies: deadline = 1 year
- Restitution of the status quo ante (reinstatement) if the deadline was missed through no fault of your own.
We assess whether subsequent correction remains legally possible.
Does the objection have suspensive effect?
No. Despite an objection, you are generally obligated to pay existing liabilities by the due date. Halting payment is only possible by filing an application for suspension of execution (AdV).
What happens after an objection is filed?
The tax office re-evaluates the assessment notice entirely. It may:
- amend the assessment in your favor,
- give notice of an intended alteration to your detriment (Verböserung), or
- reject the objection → followed by the issuance of a formal decision on the objection.
A lawsuit may be brought before the Tax Court (Finanzgericht) against the decision on the objection.
Do I need an attorney to file an objection?
Strictly legally: No. In practice: In many cases yes, because:
- complex misinterpretations are frequently overlooked
- a well-founded legal argument substantially increases the chances of success
- the tax office will only correct errors if they are clearly demonstrated
- tactically flawed objections carry risks (alteration to your detriment)
We handle the complete review and drafting of a legally sound objection.
Consultation via Video Conference
Our attorneys provide personal consultations regardless of your location – via secure video conferencing, throughout Germany.
Schedule an Appointment
Ihr Kontakt zu uns
Schildern Sie uns Ihren Fall vertraulich
Schildern Sie kurz, was passiert ist und ob Fristen oder Termine laufen. Wir melden uns in der Regel innerhalb von 24 Stunden, um das weitere Vorgehen und die benötigten Unterlagen zu klären.
Call directly